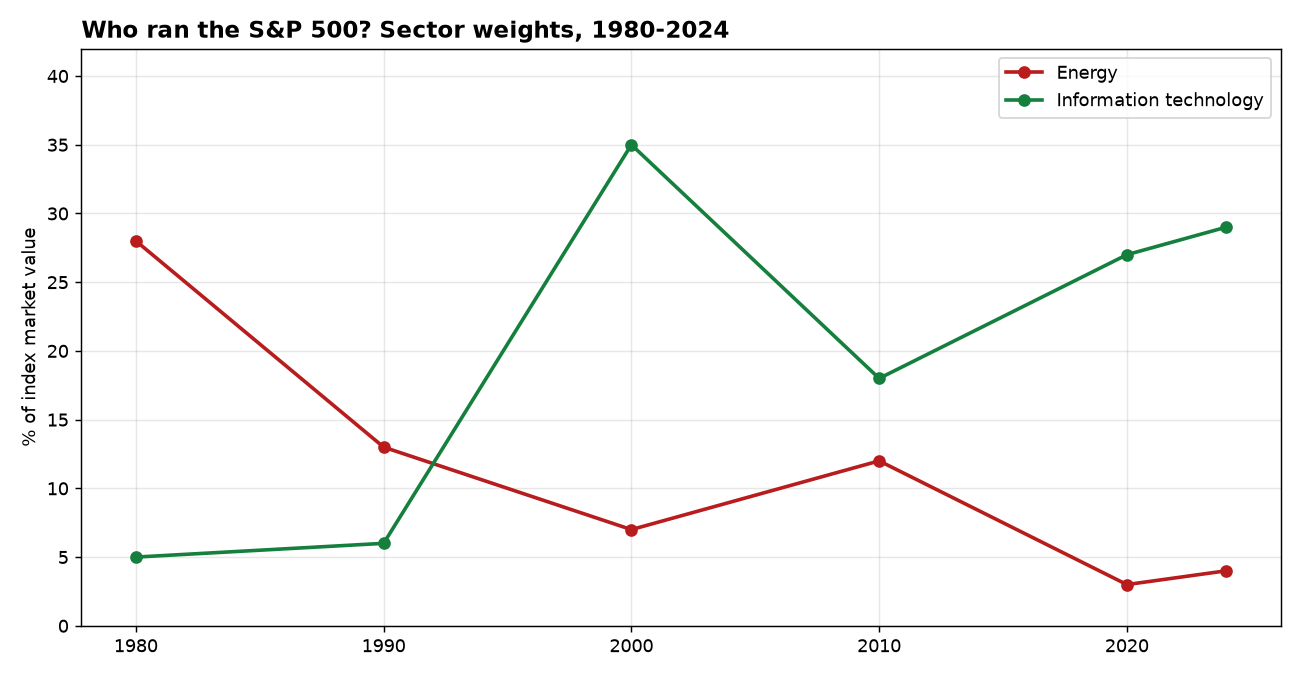
In 1980, the biggest sector in the S&P 500 (^GSPC) was energy — oil companies made up about 28% of the whole index. By 2024 energy was about 4%. The crown now belongs to information technology, at about 29% in 2024 — and nearly 40% by March 2026. The index did not change its rules. The economy changed underneath it.
The handover, in three acts
Act one — oil (1980). The 1970s oil shocks made energy giants the most valuable companies in America. Exxon was the index.
Act two — the churn (1990–2010). Energy faded (13% → 7% → 12%), technology rose to about 35% at the dot-com peak in 2000, crashed to around 15% by 2002, and climbed back to 18% by 2010. No sector held the crown for long.
Act three — tech (2020s). Information technology rose from 27% in 2020 to about 29% in 2024 — and toward 40% by 2026 — bigger than energy ever was. The five largest companies in the index are all technology names.
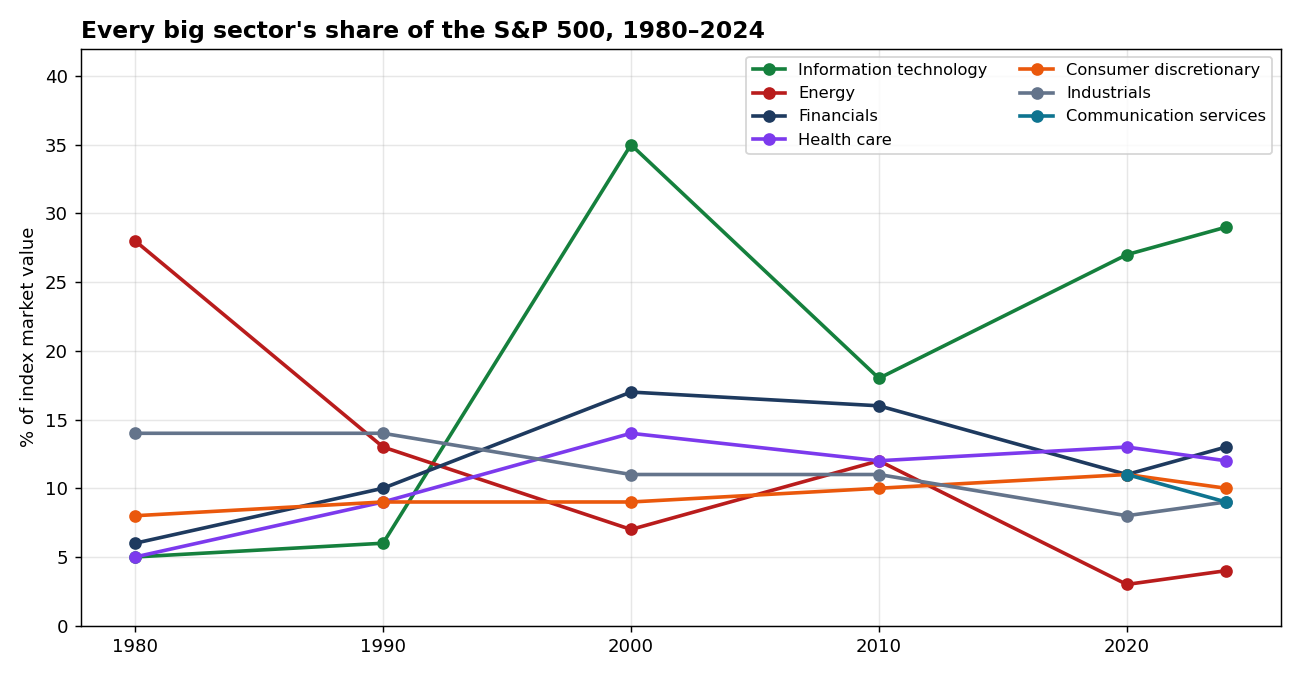
Put all seven sectors on one chart and the handover is even clearer. Energy falls from the top to the bottom, technology rises from the bottom to the top, and the other five sectors stay between 5% and 17% the whole time. Nobody else ever held the crown — the story of the index is the story of two sectors swapping places.
Why it matters
Buying “the market” in 1980 meant buying oil. Buying “the market” today means buying technology. The index is not a fixed thing — it is a mirror of the economy, and the mirror gets re-silvered every decade. That is why the winners of one era are rarely the winners of the next, and why the 5-lessons post on this blog found that most individual stocks lose to Treasury bills over their lifetimes.